Reading a quote. A quote shows two prices: bid on the left, ask on the right. If EUR/USD shows 1.08421 / 1.08433, you sell at 1.08421 and buy at 1.08433. The difference is 0.00012 — on a pair quoted to five decimal places, 1.2 pips.
Turning pips into money. Two steps:
Find the pip value for your position size. On a standard lot of 100,000 units of a USD-quoted pair, one pip is worth $10. On a mini lot (10,000 units), $1. On a micro lot (1,000 units), $0.10.
Multiply the spread in pips by that pip value.
A 1.2 pip spread on one standard lot of EUR/USD costs $12 to enter. On a micro lot, $0.12.
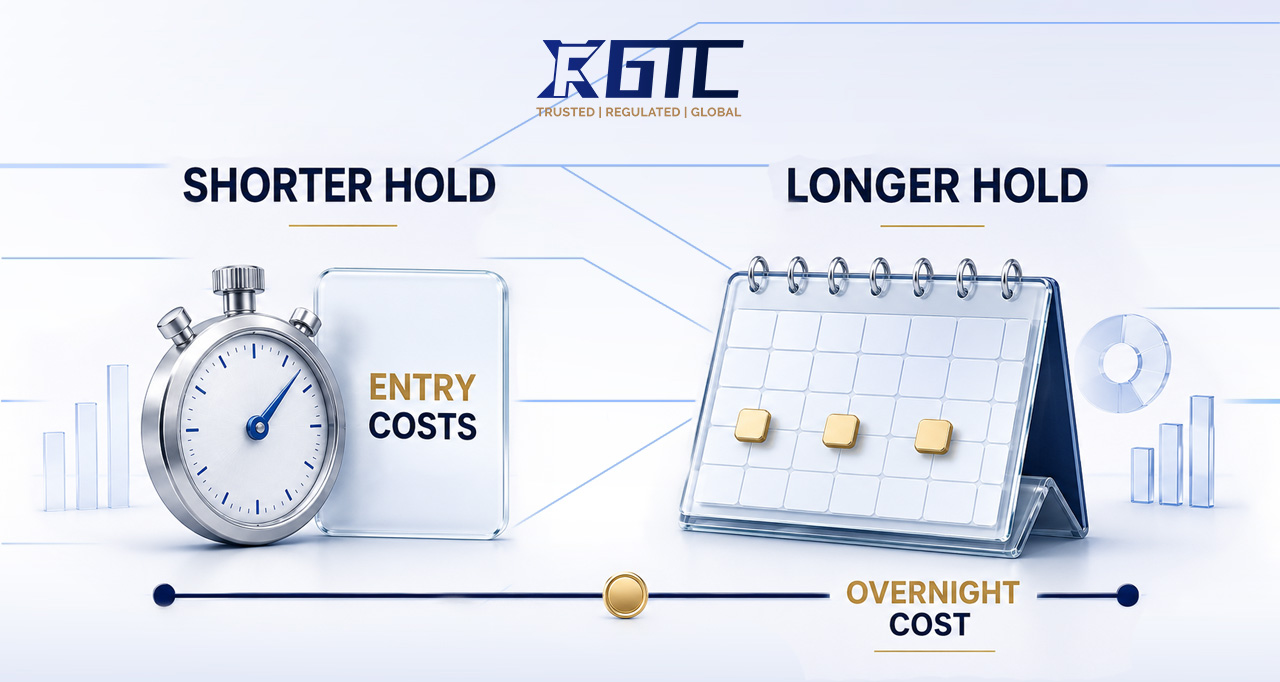
The spread is the measured gap between bid and ask; commission and overnight financing can add separate cost layers.
The same calculation on other instruments. This is where traders get caught out, because a pip is not a fixed amount of money across instruments.
| Instrument |
Spread |
Position size |
Approximate cost |
| EUR/USD |
1.2 pips |
1 standard lot |
$12 |
| EUR/USD |
1.2 pips |
1 micro lot |
$0.12 |
| Gold (XAU/USD) |
$0.30 |
1 lot (100 oz) |
$30 |
| Index CFD |
1.0 point |
1 contract at $1/point |
$1 |
The figures above are illustrative rather than quoted prices. The point is that identical-looking spread numbers on different instruments represent very different amounts of money, and the only way to know what you are paying is to run the conversion for the instrument and size you actually trade.
Fixed vs floating. A fixed spread stays constant under normal conditions; a floating spread moves with market liquidity. Most retail accounts today use floating spreads, usually tighter than fixed spreads in liquid conditions and wider when liquidity thins.
When spreads widen. Two predictable situations. Around scheduled news releases, liquidity providers pull back ahead of the announcement and spreads widen for a period around it. And at the daily rollover, when the trading day rolls to the next settlement date, spreads widen briefly during the changeover. Neither is a malfunction, and both are avoidable if you know the schedule.
Deep liquidity tends to compress the bid–ask gap; scheduled news and the daily rollover can temporarily widen it.